Logo

Category: News

Spring is a season of fresh starts, and this edition explores some of the changes reshaping the property market and our homes. From new tax

Spring is a season of fresh starts, and this edition explores some of the changes reshaping the property market and our homes. From new tax changes that could influence the future of property investment to signs the market may be shifting in favour of buyers, we unpack what these developments could mean for homeowners and aspiring investors alike.

We’re also looking inside the home, where open-plan living is making way for more flexible spaces designed to better suit modern lifestyles. Plus, you’ll find plenty of seasonal inspiration, from spring gardening tips to healthy living ideas and your chance to win $1,000 in our latest competition.

We hope this edition gives you plenty of ideas and insights to enjoy throughout the season.

Your Spring gardening checklist As most of us know, Spring is the perfect time to give your garden some TLC after the winter months. A

Your Spring gardening checklist

As most of us know, Spring is the perfect time to give your garden some TLC after the winter months. A few simple jobs now can help your plants thrive and survive in the warmer weather ahead.

1. Welcome Pollinators to Your Garden

Bees, butterflies and other pollinators play an important role in helping flowers, fruit and vegetables thrive. Encourage them into your garden by planting a variety of flowering plants, providing a shallow dish of water with a few pebbles for safe landing, and avoiding pesticides where possible.

Even a few flowering pots on a patio or balcony can help create a welcoming habitat for these important garden visitors.

2. Prune Away Winter Damage

Remove dead, damaged or diseased branches to encourage healthy new growth. Early spring is a great time to tidy roses, salvias and native grasses, while lightly trimming lavender after flowering. Always check the best pruning time for your plants, as some varieties flower on old growth.

3. Feed Your Plants

Give your garden a boost with a slow-release fertiliser or compost. Feed flowering plants to encourage colourful blooms, and don’t forget your lawn—it will appreciate a spring feed after winter.

4. Mulch to Lock in Moisture and Reduce Weeds

Apply a 5–7 cm layer of mulch to help retain moisture, regulate soil temperature and suppress weeds.

For stubborn weeds, place plain cardboard over the area before adding mulch. The cardboard blocks sunlight, helping to stop weeds from growing while naturally breaking down over time.

5. Check Your Irrigation

As the weather warms up, make sure your watering system is ready for Spring.

Check sprinklers and drippers for leaks or blockages that may have developed over Winter.

Myth vs Fact: Protein

If you’ve noticed the word “protein” appearing on everything from yoghurt to cereal bars, you’re not imagining things.

Adding more protein to your diet has become one of the biggest food trends in recent years. While it may seem like a new craze, nutrition experts have long recognised protein as an essential part of a healthy diet.

Myth #1: If it says “High Protein”, it must be a better choice.

Fact: Not all protein products are created equal.

Many foods now come in “high protein” versions, but some contain only a small amount of extra protein while also adding more sugar, fat or calories.

Top tip: Check the nutrition panel and compare products per 100g, not just per serving. Some products appear higher in protein simply because the serving size is larger meaning you could be paying more for very little extra nutritional benefit.

Myth #2: Eating protein is only for building muscles.

Fact: Protein is essential for everyone.

It helps repair and maintain muscles, supports healthy bones, aids recovery and helps keep you feeling fuller for longer. Building significant muscle takes years of consistent strength training and the right nutrition — simply eating more protein won’t make you bulky.

As we age, getting enough protein becomes even more important for maintaining muscle mass, strength, balance and contributes to your overall health.

Did You Know?

Protein isn’t just found in meat. Eggs, fish, Greek yoghurt, milk, cheese, beans, lentils, chickpeas, tofu, nuts and seeds are all excellent sources.

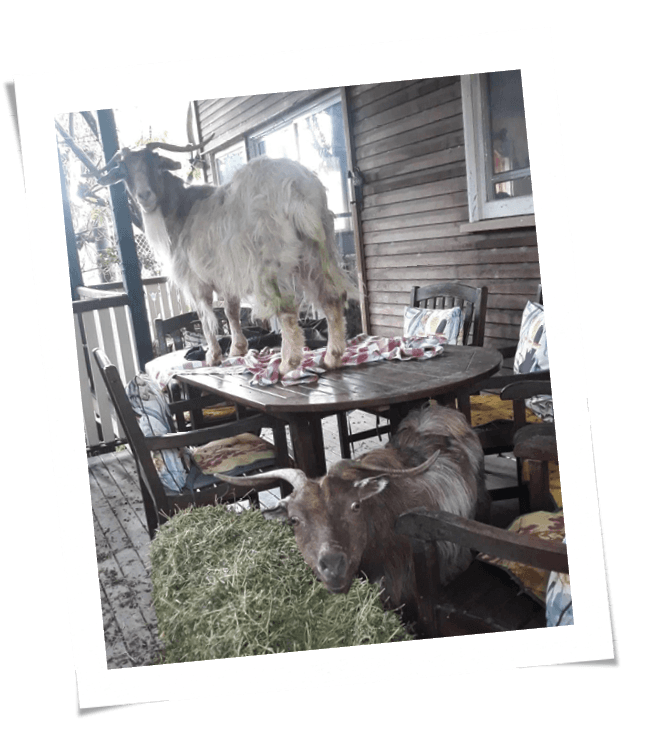
Congratulations to last edition’s winner Sara, who has taken home the $1,000 prize!

“Lulu and Ruby escaped from their pen and found the bale of hay. Lulu stood on watch while Ruby happily munched away!”

It’s clear these two cheeky goats know how to work as a team! With Lulu keeping lookout and Ruby enjoying the spoils, this mischievous moment perfectly captured the spirit of our competition.

Thank you to everyone who shared their pets’ funniest, cheekiest and most memorable moments, we loved seeing all of your wonderful entries.

WIN $1,000 Cash

The best advice I’ve ever received

We’ve all been given advice that’s stuck with us, whether it came from a parent, grandparent, teacher, friend or even a complete stranger, and we’d love to hear yours!

Tell us the best piece of advice you’ve ever received, who shared it with you and why it has stayed with you over the years for your chance to win $1,000.

How: in 350 words or fewer, send your answer to: havencompetitions@afgonline.com.au placing ‘Best advice’ in the subject line.  

Include: your name, address, email, phone number and the name of your mortgage broker.  

Dates: opens on August 5th and closes on October 10th 2026.

Winner: will be decided on October 11th and notified after this time.

T&Cs: visit http://bit.ly/HavenWin

Originally published in Haven Magazine – Spring 2026 Edition, this article has been republished on our website with permission.

How tax changes will shift the dial on property investing. The Great Australian Dream used to be home ownership but for a new generation, that

How tax changes will shift the dial on property investing.

The Great Australian Dream used to be home ownership but for a new generation, that dream has become an investment property.

And who can blame the dreamers, with prices leaping around the country in the past five years, everyone wants in on the action. In Perth, the average price of a home has doubled in the past five years, while in Brisbane it’s up 90 per cent and in Adelaide up 85 per cent, according to PropTrack’s Home Price Index.

But this year’s Federal Budget announced sweeping changes to tax rules around investing in property, which passed the Senate in late June. So, does it still stack up? The short (and annoying) answer: yes and no. But that’s pretty much how the government has planned it.

From next year, tax breaks for property investors—negative gearing and a hefty 50 per cent capital gains tax discount—will only be available to those who invest in new builds. The aim is to redirect investor cash away from existing homes and towards purchases that actually add to Australia’s housing stock.

Along with boosting housing supply, the Government hopes recalibrating incentives will also help ‘level the playing field’ for first home buyers by making existing properties less attractive and attainable for investors.

Negative gearing in a nutshell

But first, what exactly is negative gearing, who uses it and why?

For an investment property to be negatively geared, the cost of operating it (including interest payments on investment loans) must be more than the income it earns from rent. Essentially, it is operating at a loss. Under the old rules, that loss could be claimed as a deduction against the owner’s income (including salary and wages). But under planned changes, from July 1 next year, this tax offset will only be available to those who purchase a new build.

Importantly, negative gearing arrangements for existing properties purchased before changes were announced on Budget night in May, will be ‘grandfathered’ allowing owners to continue to access negative gearing tax breaks until that property is sold.

Who will this impact? Well, according to ATO data, about 230,000 taxpayers buy a negatively geared property each year. Lending data indicates roughly 80 per cent of these would be existing homes rather than new builds. So, that’s about 184,000 existing properties purchased and negatively geared each year that will be impacted by planned changes. The Government hopes much of that demand will shift to new builds, bolstering construction and supply.

But it’s not that simple. Existing homes are often favoured by investors because they rise in value much faster than new builds, with investors banking on these rising valuations over longer terms, rather than rental income, to generate profit when sold (or equity to buy another property). However, that potential profit will be hit hard by an end to the capital gains tax discount on investments on pre-existing properties.

Potential pros and cons

If the numbers don’t stack up, investors may just decide not to invest in real estate at all, leading to a reduction in the number of available rentals, and higher rents. Rents could also rise if investors try to ensure properties are positively geared (that is, that the rent covers operating expenses and loan payments).

For their part, the Federal Government estimates changes will have minimal impacts on rent, equating to around an extra $2/week on median rental costs.

Removing some investor demand from the existing home market will flatten prices but, as with rent, by how much is speculation. The Government estimates changes will shave around 2 per cent off average home price growth over the next two years. Commonwealth Bank modelling estimated a 3 per cent pull back, with prices already softening. (See our Market Shift story in this edition of Haven)

On the flipside, Treasury figures estimate reduced competition from investors will lead to an additional 75,000 owner-occupiers entering the market over the next decade.

Aside from rent and house price impacts, some commentators have suggested the necessary ‘grandfathering’ arrangements around negatively-geared existing properties (purchased before changes were announced) may impact supply as owners may choose to hold these longer to maintain tax advantages.

Also, in a late change to get their Bill through the Senate, the Government agreed to end Limited Recourse Borrowing Arrangements (LRBAs) to buy residential properties through Self-Managed Super Funds (SMSFs), which had become an increasingly popular investment strategy.

There is some concern increased competition from investors could push up prices in the new builds market if the construction industry cannot respond to increased demand.

What is a new build?

What exactly is a ‘new build’? At present, the Government defines it as a residential property which ‘genuinely adds to supply’.

That does not include:

  • Knock down rebuilds or substantial renovations;
  • Granny flats added to existing properties; and
  • Properties that have been occupied for more than 12 months before first sale.

It does include:

  • House and land packages on vacant land
  • Off the plan apartments and newly-constructed townhouses.
  • Duplex developments. For example, if an existing house is demolished and two townhouses are built, these would both qualify as new-builds because they add to the overall housing supply. That means in-fill duplex developments in prime suburbs could become a lot more attractive to developers.

One thing is certain — this is the biggest change to property investingin a generation and while the impact may be felt immediately, the true outcome may not be known for years.

Originally published in Haven Magazine – Spring 2026 Edition, this article has been republished on our website with permission.
For the first time in years, buyers hold the power but will they use it? Australia’s housing market has cooled rapidly this year as buyers

For the first time in years, buyers hold the power but will they use it?

Australia’s housing market has cooled rapidly this year as buyers grapple with the prospect of higher rates for longer, global instability and a major shift in tax settings.

Auction clearance rates slumped to their lowest levels since 2020 this winter, and houses are sitting on the market longer – or being withdrawn from sale altogether – as sellers, too, struggle to adjust price expectations. In the last week of June, the national auction clearance rate dipped to 45 per cent, well below the rate at the same time last year, which was buoyant, around 68 per cent, according to Cotality.

While the slowdown has handed buyers more negotiating power than they’ve had in years, many are nervous about jumping in, fearing a significant market correction is on the horizon. Ironically, that could hand even more negotiating power to those still on the hunt.

Slowdown or correction?

Nationally, home prices fell 0.4 per cent in June, the third consecutive monthly drop, according to PropTrack’s Home Price Index. Prior to this run, the only other price dip in the past four years was in December/January of 2024/25, but the market bounced back quickly when the Reserve Bank of Australia began cutting interest rates from the long term high of 4.35 per cent.

But this time around, there are no rate cuts on the horizon and multiple headwinds, which commentators believe will extend this buyers’ market through the remainder of 2026. The three main factors putting downward pressure on prices are:

1. Global instability

The long-term future of the Strait of Hormuz is still to be ironed out, but in the meantime, it is causing price inflation in the construction sector which is flowing through to house prices and supply. A Commonwealth Bank report in May 2026 noted the price of PVC piping had leapt by as much as 40 per cent and surcharges of up to 25 per cent were being charged on concrete deliveries due to the US/Iran conflict. It’s driving up the price of both new builds and renovations.

2. Tax changes

In late June, the Federal Government passed sweeping changes to tax breaks for property investors which will restrict negative gearing deductions to new builds (see our story in this issue) and end capital gains tax discounts for investors who buy pre-existing homes. The aim is to cut the number of investors competing against first-home buyers. Investors will be further stymied by a late change to legislation, passed in late June, that will block loans to buy residential property held in Self-Managed Super Funds. While the Government estimates this lowering of demand will shave two per cent from annual price growth over the two years, analyst Morgan Stanley has said it will be a more significant 5-10 per cent.

The changes announced on Budget night in May seemed to have an immediate impact on the market. Unlike transient impacts from war and interest rates, this is long-term structural change to cool the market.

3. Interest rates

Three rate hikes – in February, March and May this year* – on top of a globally-driven inflation spike has stressed household budgets and slashed borrowing capacity. While most economists believe we have hit the top of the rates cycle, none of the big four Banks see a rate cut arriving before the middle of 2027.

It’s interesting to note that while nationally average price growth has stalled, this has primarily been led by significant falls in capital cities, with regional prices growth holding up, indicating buyers are chasing value. Demographers have also noted a strong re-emergence in 2026 of the ‘tree-change’ phenomena that saw people leaving capital cities for regional centres during Covid years.

The takeaways

While prices are flattening, it comes off historic gains.

So, despite recent monthly falls, from June 2025 to June 2026 the market is still up 5.8 per cent overall with significant variance by capitals. Year-on-year Perth is up 17.1 per cent, Darwin 16.7 per cent and Brisbane by 13.9 per cent.

Sellers need to adjust expectations.

Analysts have noted a spike in homes quietly being withdrawn from the market after unsuccessful campaigns, with sellers hoping to wait out a flat period. The slump in auction clearance rates is a clear indicator prices are out of step with what buyers are now willing and able to pay.

Buyers have room to negotiate.

Property market observers say buyers are increasingly willing to accept an early offer rather than roll the dice and take a property to auction. In a falling or flat market there is always the concern conditions will deteriorate further and buyers can use this to their advantage. Always check how long a property has been on the market before making an offer.

Few people want to tackle a ‘renovators’ delight.

With construction costs once again climbing sharply, and interest rates uncertain, it’s a brave buyer who will tackle the unknown of a renovation project. Sellers can no longer price for potential and will take a hit if a property needs work.

Potential for increased new build demand.

While the Federal Government hopes investor cash will shift to new builds and bump up supply, if Australia’s construction industry can’t respond to an uptick in demand, it could increase prices in that market.

Whether this proves to be a brief slowdown or a deeper correction, buyers ready to negotiate hard for a long-term purchase have more leverage than they have had in years.

*Interest rate references are accurate as at July 2026 and may change over time.

Originally published in Haven Magazine – Spring 2026 Edition, this article has been republished on our website with permission.
The case for breaking up open plan spaces to create cosy nooks. After decades of dominance both in the workplace and at home, open plan

The case for breaking up open plan spaces to create cosy nooks.

After decades of dominance both in the workplace and at home, open plan design is giving way to a more considered ‘broken plan’ aesthetic.

It’s a trend that’s easy to understand when you consider how a room ‘feels’ rather than how it looks. Because, while open plan living is many things – flexible, bright, spacious — one thing it is not, is cosy.

But with a few clever design tweaks, it’s possible to create several clearly defined spaces within one large space, nudging open plan to a much more comfortable and functional layout dubbed broken plan, or micro-zoning.

Intriguingly, there’s a long-standing architectural and psychological theory behind this design trend: Prospect-Refuge Theory. Developed in the 1970s, the theory proposes that humans are naturally drawn to spaces that offer a clear view of their surroundings (prospect), while also providing a sense of shelter (refuge), from the wider world. It’s why we might be drawn to a reading chair tucked away in the corner of a room. These ‘safe’ spaces allow for a greater sense of calm and relaxation.

Through the 1980s designers started tearing down internal walls to maximise sightlines but in doing so lost the sense of refuge quiet corners provided. The first sign of revolt was the rise of Scandinavian cosiness trend hygge (pronounced hoo-gah) in 2016. Then Covid hit and we found out, not only were our open plan homes not particularly hygge, they weren’t all that functional either.

The major drawbacks to open plan design are:

  • It can be noisy with sound bouncing off multiple hard surfaces.
  • Limited wall space makes it tricky to place furniture, TVs and artwork.
  • Visual clutter can be overwhelming and it is difficult to keep uniformly tidy.
  • Limited privacy, meaning it doesn’t work as a multi-function space.
  • It’s an inefficient use of space.

Micro-zoning

The trending design solution to these open plan issues is to carve out deliberate micro-zones — an office corner, a reading nook, a TV zone, a dining area.

Using plants, furniture, textiles and lighting to divide the larger space into these smaller zones creates a sense of privacy and separation without sacrificing flow. It serves a growing need for living areas to be multifunctional, without major structural change.

Here’s some tips on how to achieve a broken plan feel.

1. Lighting

Bright, even lighting is best left for offices and work spaces. In the home, lighting should actually be uneven, with pools of light and shade defining different living areas. The key to micro zoning is creating layers with light, the same way designers would use textures and colours. For example, a low light suspended over a dining table defines that zone for intimate meals, just as a lamp in a dark corner next to a cosy chair designates it as a reading and relaxing nook. Vary the direction, height and source of lighting, with ceiling lights in some areas, lamps in others and a backlit glow to highlight architectural features.

2. Colours

An easy way to make a room feel sterile is to stick to a single neutral tone for walls and furnishings. Spaces need varied depth of colours to hold interest, which is not to be confused with garish ‘pops’. Go for deeper shades of the same palette and make sure not to mix cool and warm tones. Changes in colour tones — or if you’re brave some statement wallpaper —can really help define and separate different areas.

3. Natural Fibres

Modern, open plan designs are often dominated by hard, reflective surfaces such as stone, glass and metal. Soften and add warmth to relaxation zones with natural elements that will absorb light rather than bounce it around. Incorporate brick, wood and textiles. Plants can do double duty, making spaces feel more relaxed, while also providing privacy screening.

4. Floors and ceilings

The easiest way to create a distinct zone is a large rug under furniture. But there is also a strong trend to flip the script and go for a ceiling treatment. Plywood or wood panelling that climbs the walls and extends across the ceiling is particularly on trend.

5. Furniture

Strategically placed furniture helps create nooks and zones. Open shelving is the perfect way to divide spaces without blocking light — take a cue from mid-century styling which commonly uses indoor planters, half-height walls and shelving to carve out private areas. Banquette seating in dining areas can create a cosy sense of enclosure, but is also space-efficient compared to multiple chairs. Occasional chairs can be hero pieces in broken plan design.

Lastly, remember to be intentional. This is not about adding random décor for the sake of it. Think about how you use spaces and create zones accordingly. If there is a sunny spot near a window — perhaps it’s the spot to create a morning coffee nook. Get it right and you will not only have a more beautiful and welcoming home, you will have a much more functional one too.

Originally published in Haven Magazine – Spring 2026 Edition, this article has been republished on our website with permission.
At its meeting today, the Reserve Bank of Australia (RBA) has held the cash rate at 4.35%. The Reserve Bank of Australia (RBA) has today

At its meeting today, the Reserve Bank of Australia (RBA) has held the cash rate at 4.35%.

The Reserve Bank of Australia (RBA) has today decided to keep the cash rate unchanged at 4.35%, giving borrowers some welcome stability while it assesses how recent rate increases are flowing through the economy.

Inflation has shown some encouraging signs of easing, with annual headline inflation falling to 3.8% in June 2026, down from 4.0% in May 2026. However, underlying inflation remains higher than the RBA would like, with trimmed mean inflation holding at 3.6%.

With the temporary fuel excise reduction ending in early August 2026, petrol prices are expected to lift as the full excise is reinstated. This could add some upward pressure to headline inflation in the coming months and will be another factor for the RBA to monitor.

What could this mean for you?

Even when rates stay unchanged, your home loan doesn’t have to. It could be a good time to review your current rate, repayments and loan structure to make sure they still suit you.

Whether you’re planning ahead or simply want to explore your options, I’m here to help.

At its meeting today, the Reserve Bank of Australia (RBA) has held the cash rate at 4.35%. Today’s decision reflects the RBA’s cautious approach as

At its meeting today, the Reserve Bank of Australia (RBA) has held the cash rate at 4.35%.

Today’s decision reflects the RBA’s cautious approach as it continues to assess inflation, economic growth and the impact of previous interest rate changes.

While inflation remains above the RBA’s target range, higher interest rates continue to weigh on household spending and broader economic activity. There also remains uncertainty around property prices following last month’s proposed taxation changes.

In a changing economic environment, staying informed about interest rate movements and how they may affect your financial position is important.

Whether you’re planning ahead or simply want to explore your options, I’m here to help.

From the rise of natural swimming pools, offering a more sustainable way to enjoy the outdoors year-round, to the growing influence of the Bank of

From the rise of natural swimming pools, offering a more sustainable way to enjoy the outdoors year-round, to the growing influence of the Bank of Mum and Dad in today’s property market, this edition covers the shifts shaping how Australians live. With energy costs front of mind this winter, it also highlights simple ways to uncover savings hiding in plain sight.

Whether you’re looking to create a more efficient home, plan your next move, or simply embrace the slower pace of winter, we hope this edition inspires you.

At its meeting today, the Reserve Bank of Australia (RBA) has increased the cash rate by 0.25%, with the official cash rate now sitting at

At its meeting today, the Reserve Bank of Australia (RBA) has increased the cash rate by 0.25%, with the official cash rate now sitting at 4.35%. 

Today’s decision reinforces the RBA’s ongoing priority to bring inflation back within its 2–3% target range. The decision was supported by data released last week which showed inflation has continued to increase, largely due to global conflict-driven supply issues and higher fuel costs.

The data highlighted:

  1. Headline inflation has risen to 4.6% for the 12 months to March 2026, up from 3.7% in February 2026.
  2. Underlying (trimmed mean) inflation sits at 3.3%.

Fuel price inflation can take time to unwind, meaning price pressures may remain elevated even if broader economic conditions begin to stabilise. As the RBA navigates this more complex environment, staying informed about interest rate movements and what they mean for your financial position is increasingly important.

Whether you’re considering purchasing a home, refinancing to review your loan structure, or exploring investment opportunities, now is a timely opportunity to review your current lending arrangements and future plans.

As widely anticipated, the Reserve Bank of Australia (RBA) has increased the cash rate by 0.25% at today’s meeting, taking the official cash rate to

As widely anticipated, the Reserve Bank of Australia (RBA) has increased the cash rate by 0.25% at today’s meeting, taking the official cash rate to 4.10%.

The decision reflects the RBA’s ongoing focus on returning inflation to its 2-3% target range, with the latest data showing inflation pressures remain elevated.

Recent economic indicators highlight:

  • Headline inflation sits at 3.8% for the 12 months to January 2026, remaining above the RBA’s target range.
  • Underlying (trimmed mean) inflation remains elevated at 3.4% for the 12 months to January 2026, signalling that broader price pressures across the economy are persisting.

The decision comes amid heightened uncertainty in the global economic environment, with ongoing geopolitical tensions contributing to volatility in energy and petrol prices. These developments typically flow through to higher transport and production costs across the economy, which can add to inflationary pressures at a time when inflation remains above the RBA’s target range.

In a changing economic environment, staying informed about interest rate movements and how they may affect your financial position is important.

Whether you’re considering purchasing a home, refinancing to review your loan structure, or exploring investment opportunities, it may be a good time to review your current lending arrangements and future plans.